
KAMPALA, September 20, 2026 – Ugandan Savings and Credit Cooperative Organisations [SACCOs] have been urged to go beyond providing agricultural credit by integrating insurance into their services to help farmers protect their investments against production-related risks.
The proposal would see SACCOs incorporate agricultural insurance into their lending and member-support programmes, potentially protecting both farmers and lenders from losses arising from crop failure, livestock losses and other agricultural risks.
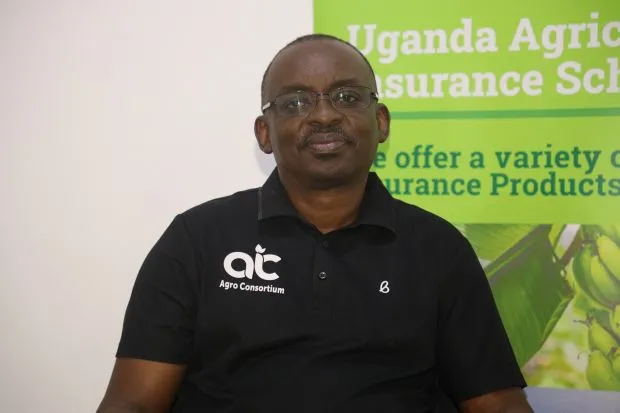
Speaking to theCooperator News in an exclusive interview, John Makosya, Chief Operations and Impact Officer at Agro Consortium Uganda Limited, said SACCOs should consider insuring agricultural loans extended to their members.
“What is stopping the SACCOs from insuring those loans they are giving to their members?” Makosya asked.
He said SACCOs could also help farmers insure the expected output or yields from their agricultural investments, particularly where loan repayment depends heavily on the performance of a farming enterprise.
Agricultural finance is an important component of SACCO services, particularly in rural communities where farmers rely on cooperative financial institutions to access money for inputs, land preparation, equipment, livestock and other production expenses.
However, unlike many conventional forms of lending, agricultural credit is exposed to risks beyond the borrower’s control. Drought, excessive rainfall, pests and diseases, livestock losses and other production shocks can affect a farmer’s income and, consequently, their ability to repay a loan.
Makosya said integrating insurance into agricultural finance could therefore provide farmers with an additional layer of protection while helping SACCOs manage some of the risks associated with agricultural lending.
Rather than treating insurance as a separate financial product, SACCOs could work with insurance companies to make appropriate agricultural cover available alongside selected loans.
Under such arrangements, SACCOs could help members understand available insurance products and facilitate access to cover for crops, livestock and other agricultural investments.
For SACCOs financing farmers organised through producer groups and cooperatives, agricultural insurance could also form part of a wider package of value-chain services, linking access to credit with production support and risk management.
However, the success of such an approach would depend on the design of the insurance products and the ability of farmers to understand and afford them.
SACCOs would need to clearly communicate the risks covered, the premiums payable, exclusions and the conditions under which claims can be made and paid.
Makosya also pointed to technology as a potential tool for reducing the cost and administrative burden of agricultural insurance, particularly for smallholder farmers who are spread across large geographical areas.
“Leverage satellite data, GPS mapping, and weather analytics to monitor farmers remotely, reduce field visits, and lower administrative costs for smallholder farmers,” he said.
Such technologies could support SACCO-insurer partnerships by helping identify insured farms, monitor weather and agricultural conditions, and maintain more accurate information on farmers and their agricultural activities.
Technology could also reduce the need for frequent physical field visits, although its effectiveness would depend on the type of insurance product, the availability and reliability of data, and the systems used by insurers and SACCOs.
Despite the potential benefits, SACCOs would need to address several practical issues before incorporating agricultural insurance into their member services.
These include farmers’ understanding of insurance, the affordability and payment of premiums, the risks covered, claims assessment and the time taken to settle legitimate claims.
SACCOs would also need to ensure that members understand the distinction between a loan and an insurance policy. Taking insurance alongside a loan would not necessarily mean that every agricultural loss would be compensated, as claims would remain subject to the terms and conditions of the particular policy.
The proposal comes as SACCOs continue to play an important role in expanding access to financial services for farmers and other rural-based enterprises.
For cooperatives, incorporating insurance into agricultural finance could broaden the range of services available to members while strengthening the link between access to credit and the management of risks that can undermine agricultural investments.
The approach, however, would require appropriate partnerships between SACCOs and licensed insurers, suitable agricultural insurance products and effective systems for educating members, administering policies and processing claims.
For more info on agricultural insurance, please visit: https://www.aic.ug/
https://thecooperator.news/can-agricultural-insurance-shield-ugandas-farmers-from-el-nino/
Buy your copy of thecooperator magazine from one of our country-wide vending points or an e-copy on emag.thecooperator.news
-

-

-

-


